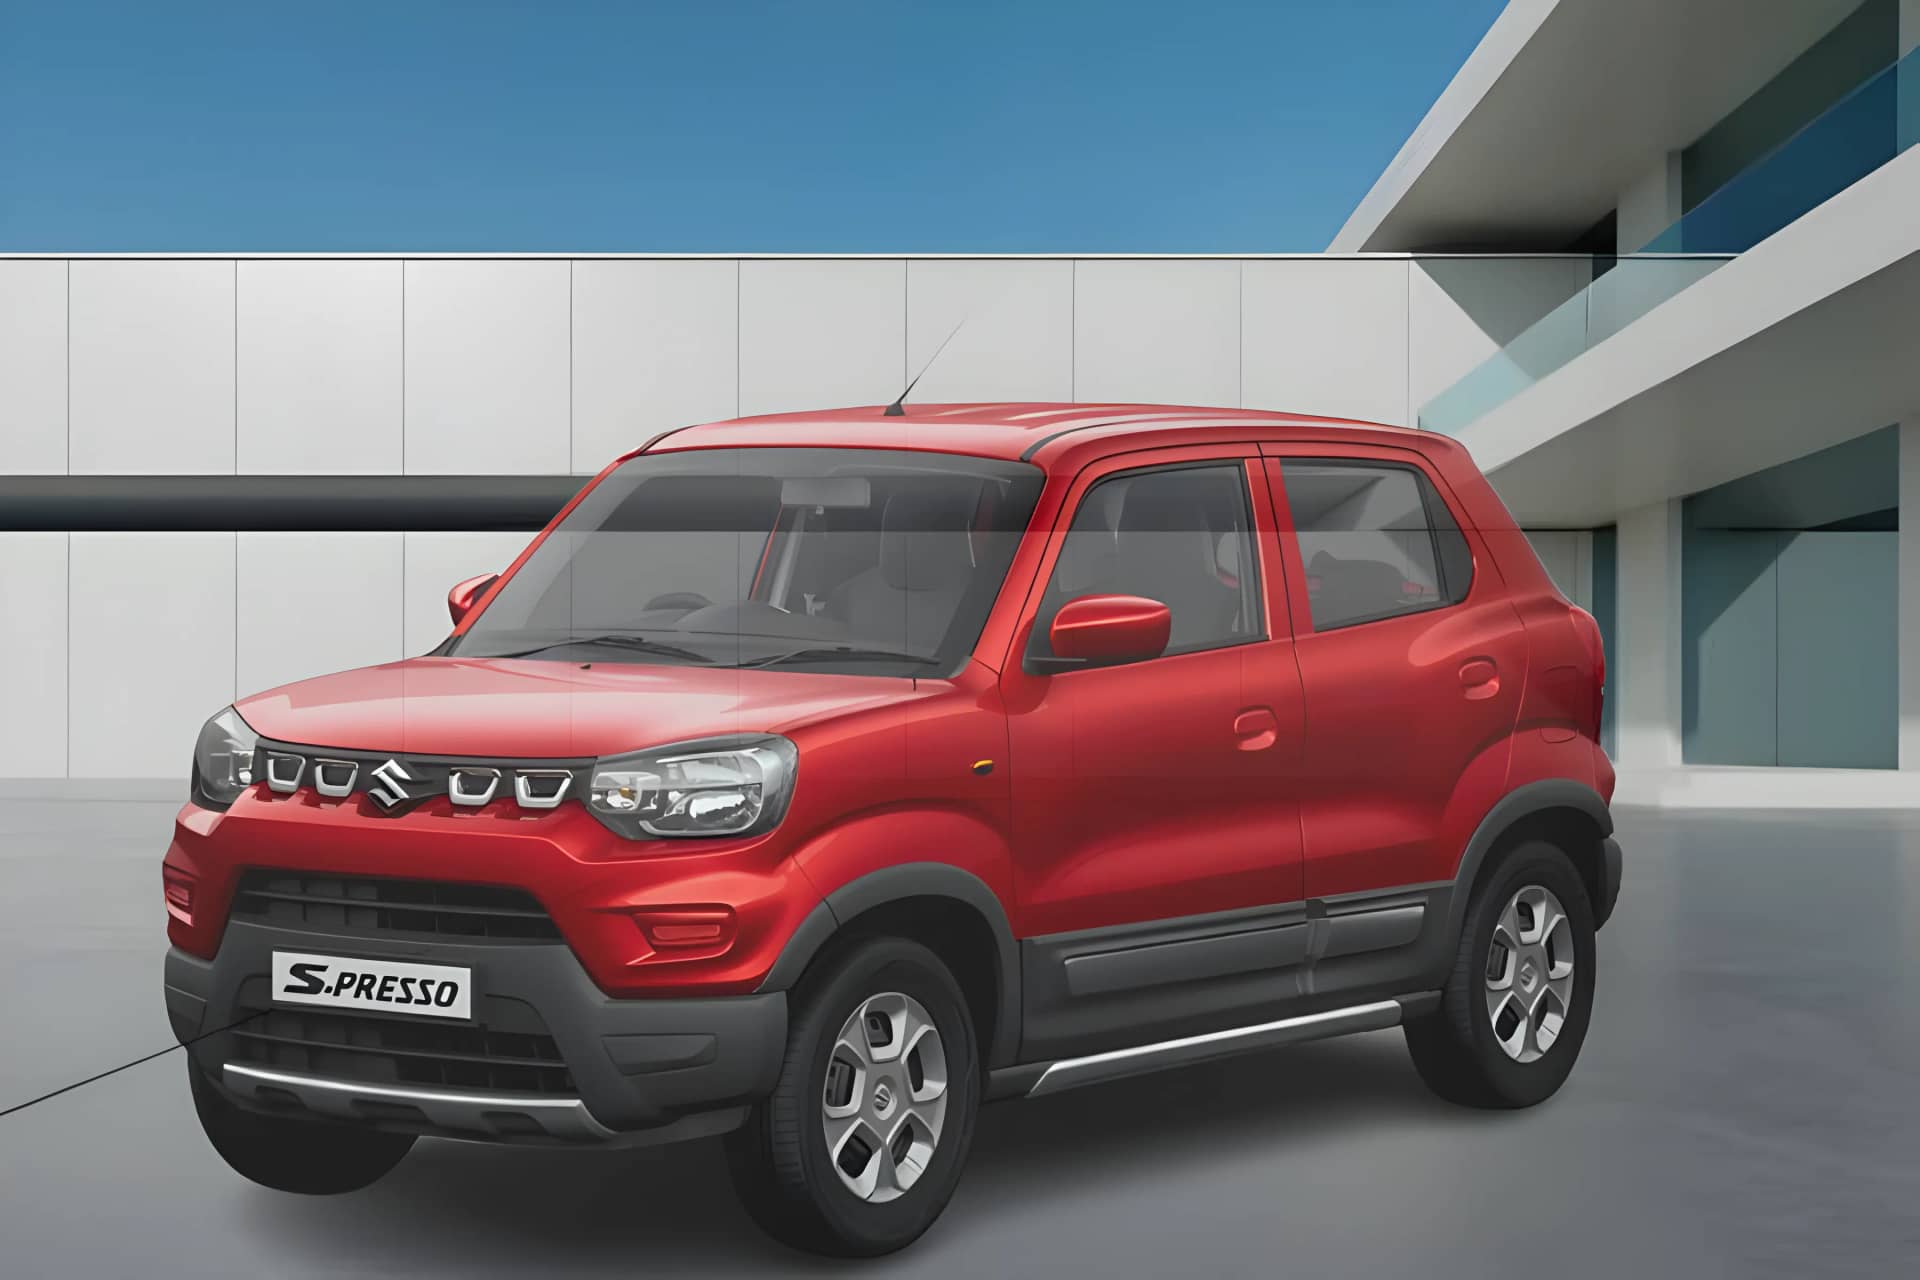
Maruti Suzuki S Presso STD (O) EMI (Base Model) is ₹7,309/mo calculated at 90% of On road price for tenure of 60 months and rate of Interest 9.5%. Maruti Suzuki S Presso Ex showroom Price and Onroad Price will increase with Variants. So EMI will also hike up accordingly. EMI varies with On road price and CIBIL Score. Bank & Finance Companies offer 70-95% Loan (funding) on On road Price for new cars and rate of interest is 8.50% -14%. Banks offer loan for maximum 5 years (60 Months) on cars.
| Maruti Suzuki S Presso Variant Name | On-Road Price in New Delhi | Estimated EMI in New Delhi 3 Years/36 Months | Estimated EMI in New Delhi 5 Years/60 Months | Estimated EMI in New Delhi 7 Years/84 Months |
|---|---|---|---|---|
| S Presso STD (O) | ₹3,86,660 | ₹11,147 | ₹7,309 | ₹5,688 |
| S Presso LXI (O) | ₹4,21,623 | ₹12,155 | ₹7,969 | ₹6,202 |
| S Presso VXI (O) | ₹4,75,411 | ₹13,706 | ₹8,986 | ₹6,993 |
| S Presso LXI (O) | ₹5,09,836 | ₹14,698 | ₹9,637 | ₹7,499 |
| S Presso VXI (O) | ₹5,23,821 | ₹15,102 | ₹9,901 | ₹7,705 |
| S Presso VXI Plus (O) | ₹5,29,200 | ₹15,257 | ₹10,003 | ₹7,784 |
| S Presso VXI (O) | ₹5,63,625 | ₹16,249 | ₹10,653 | ₹8,291 |
| S Presso VXI Plus (O) | ₹5,77,610 | ₹16,652 | ₹10,918 | ₹8,496 |
Choose model to update base price
On-Road Price
For 60 months @ 9.5% p.a.
Estimated EMI
3 Year
₹11,147
5 Year
₹7,309
7 Year
₹5,688
On-Road Price
Estimated EMI
3 Year
₹12,155
5 Year
₹7,969
7 Year
₹6,202
On-Road Price
Estimated EMI
3 Year
₹13,706
5 Year
₹8,986
7 Year
₹6,993
On-Road Price
Estimated EMI
3 Year
₹15,102
5 Year
₹9,901
7 Year
₹7,705
On-Road Price
Estimated EMI
3 Year
₹15,257
5 Year
₹10,003
7 Year
₹7,784
On-Road Price
Estimated EMI
3 Year
₹16,652
5 Year
₹10,918
7 Year
₹8,496
On-Road Price
Understanding the EMI for a Maruti Suzuki S Presso Cars is important when planning your vehicle purchase. Your monthly EMI can affect your budget, credit profile, total interest cost and overall financial planning.
A manageable Maruti Suzuki S Presso Cars EMI should fit comfortably within your monthly budget while allowing you to meet other financial commitments without unnecessary financial pressure.
Timely EMI payments on your Maruti Suzuki S Presso Cars loan can help build a positive credit history, while delayed or missed payments may negatively affect your credit profile.
The loan tenure directly affects the total interest paid for your Maruti Suzuki S Presso Cars. A shorter tenure generally means higher monthly EMIs but lower overall interest, while a longer tenure reduces the EMI but may increase the total interest cost.
Choosing the right tenure for your Maruti Suzuki S Presso Cars loan involves balancing a higher EMI over a shorter period against a lower EMI over a longer period.
Regular Maruti Suzuki S Presso Cars EMI payments can encourage disciplined financial planning and help you manage your vehicle loan responsibly.
Banks generally provide around 70% to 95% funding of the on-road price of a new vehicle. Interest rates may vary depending on the lender, loan tenure and borrower profile.
Maruti Suzuki S Presso can be financed through banks and finance companies. For Maruti Suzuki S Presso banks generally provide 70% to 95% funding on the on-road price of a new vehicle. Interest rates range between 8.5% to 14%.
Your loan eligibility and final interest rate depend on your CIBIL Score and financial profile and last repayment history.
For Maruti Suzuki S Presso, your loan amount, down payment, interest rate and EMI depend on the variant, on-road price, loan tenure, your CIBIL score and repayment history.
The Maruti Suzuki S Presso is available in multiple variants including S Presso STD (O) - Petrol - Manual, S Presso LXI (O) - Petrol - Manual, S Presso VXI (O) - Petrol - Manual, S Presso LXI (O) - CNG - Manual.
Your Maruti Suzuki S Presso EMI varies based on the loan amount, interest rate, down payment and tenure. A higher-priced variant generally means a higher EMI.
A higher CIBIL Score improves your chances of getting higher funding at a lower interest rate.